This guide is educational, not personalized financial, legal or security advice. A checklist reduces avoidable mistakes; it cannot make a transaction risk-free.
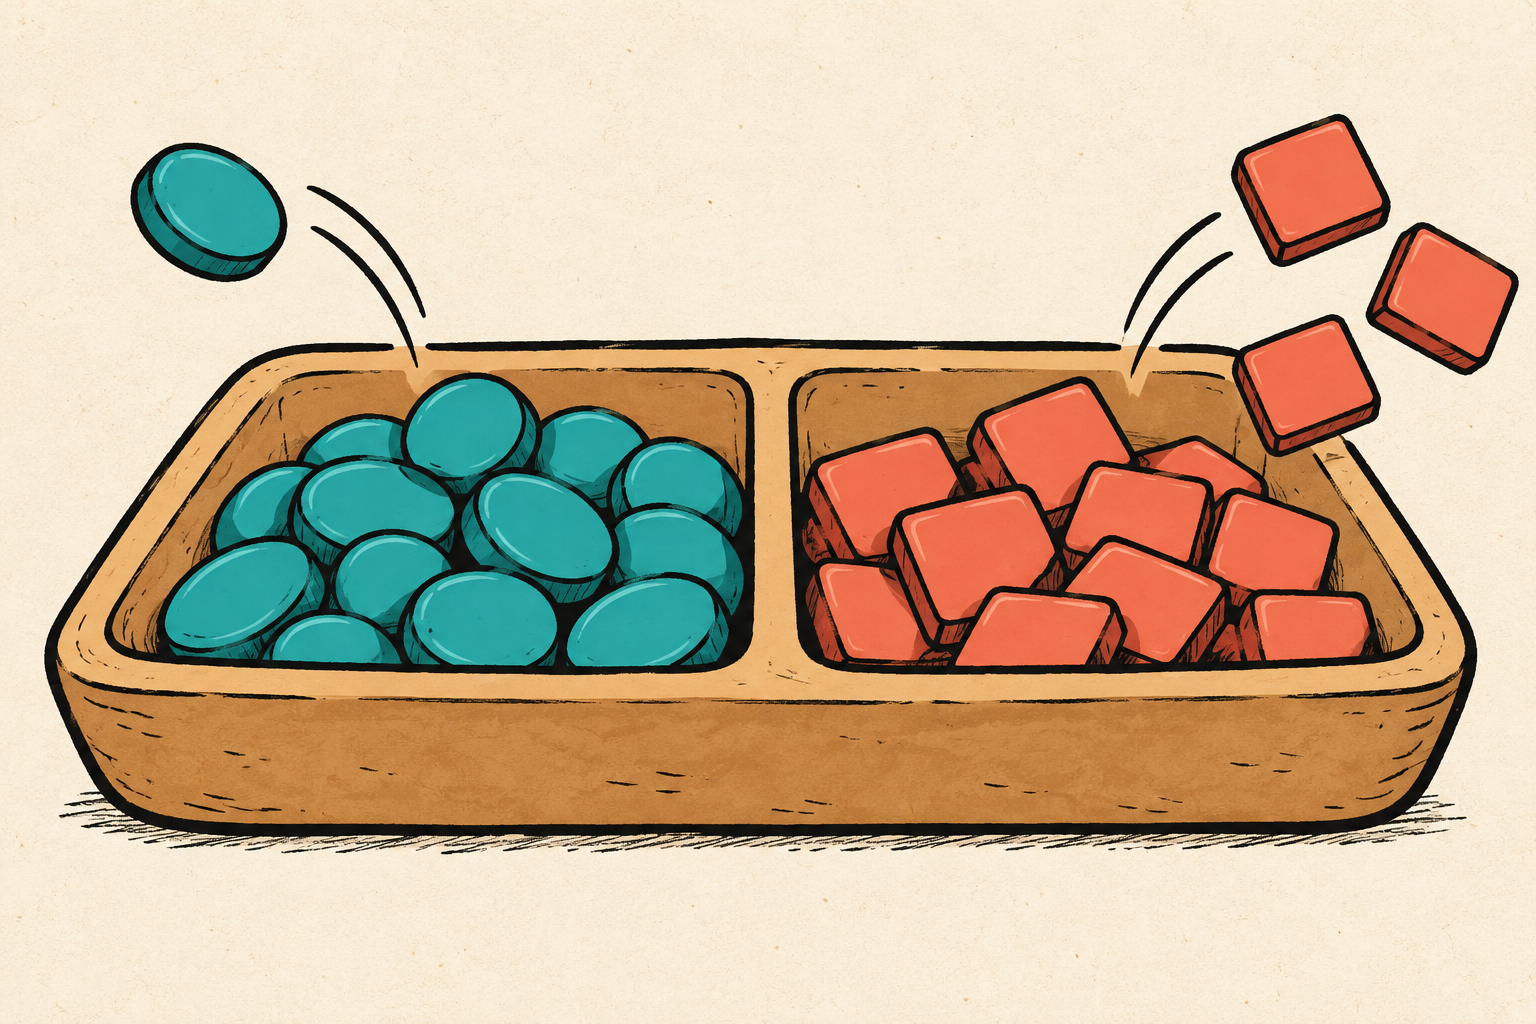

This is one simplified pool model with invented amounts and no fees. Real pools can use different rules, fees and liquidity ranges; the example is not a live quote.
- Before: the fictional pool has 100 A and 10,000 B, a starting reserve ratio of 100 B per A.
- The fee-free constant-product example adds 10 A and returns about 909.09 B.
- After: the pool has 110 A and about 9,090.91 B; the example's average output rate is about 90.91 B per A.
- The trade itself changes the pool rate (price impact); movement while a transaction waits is slippage.
Which amount is invented, what happens to each reserve, and what assumption lets you calculate the output? Explain how a later market move would be different from price impact.
What is a liquidity pool?
A liquidity pool is a set of digital assets held by a smart contract under a protocol's rules. A pool-based decentralized exchange (DEX) can use those reserves to quote and execute swaps without matching each trade to a specific posted order. Not every DEX uses pools: some use on-chain order books, and an aggregator may route one swap across several sources.
In a pool swap, a trader sends in one asset and receives another from the pool. The pool's pricing rules and available liquidity determine how much can come out. A pool is not a promise of a fixed exchange rate, and a token appearing in a pool is not proof that it is legitimate or safe. For an overview of how pool-based exchanges differ from order books, see what decentralized finance is.
How a pool swap changes reserves
Uniswap is one example of an automated market maker (AMM). Its current developer documentation describes pools with two token reserves and explains that swaps trade against those reserves. In the simplified constant-product model, the reserve amounts are represented as x × y = k. This formula describes one pool design, not every DEX or every AMM. Other models can use different rules or concentrate liquidity within selected price ranges.
Imagine a fictional pool holding 100 units of Token A and 10,000 units of Token B. Before a trade, the reserve ratio is 100 B for each A. If a trader adds 10 A, a fee-free constant-product example leaves about 9,090.91 B in the pool, so about 909.09 B comes out. The trader's average output is about 90.91 B per A—not the starting 100. That difference is price impact: the trade itself changes the pool's relative reserves and rate. These invented numbers illustrate the model; they are not a live quote. Actual output depends on the pool's exact rules, fees and route.
Price impact is not slippage
Price impact is the effect of your trade size on the price as it uses available liquidity. For the same pool and rules, a trade that is large relative to liquidity usually moves the rate more than a smaller one. Slippage is a change between the quote and execution while a transaction is pending—for example, because other trades change the market first. A swap can involve both.
Before confirming a real swap, review the input and estimated output, route, pool or protocol fees, network fee, price impact, and minimum output or other execution limit shown by the wallet or interface. A minimum-output check can reject execution below the value you chose; it does not establish that the route, token or quoted price is good. Fees and protections vary by protocol, pool and interface.
If someone supplies assets to a pool
A liquidity provider (LP) deposits assets according to a pool's rules and may receive a share of fees or other returns under that protocol's terms. This is not a savings account or guaranteed income. The value of a position can differ from simply holding the same assets, and smart-contract, token, liquidity and administrator risks depend on the specific pool. Read impermanent loss explained before comparing a pool position with holding.
A no-money practice check
Use the diagram above to compare the fictional pool before and after a swap. Which reserve changed, how did the average output rate move, and which exact pool assumption made the arithmetic possible? Then explain how price impact differs from a price change that happens while a transaction waits.
For another view of trade-size effects, read liquidity and price impact and slippage versus price impact. You do not need to connect a wallet, approve a contract or deposit assets to learn these mechanics.
Check your understanding.
Which statement correctly separates price impact from slippage?
A correct answer records local learning progress, not a qualification or proof of financial readiness.
Put this lesson in context
Learn the underlying mechanism before comparing an application or a quoted return.
Sources & context
- Uniswap Developers — How Uniswap Works ↗Consulted 2026-10-09
- Uniswap Developers — Understanding Swaps on Uniswap ↗Consulted 2026-10-09
Original educational content prepared for this project. Sources provide context, not endorsement or a guarantee that every statement remains current. Rules, product interfaces and availability can change.
Keep learning in Telegram.
Open this published guide in the learning bot. No account connection or wallet is needed.
Join the $STONKB community.
Follow project updates, share useful ideas and meet other builders. You do not need to buy $STONKB to join.
Take what you learned.
Leave the pressure behind.