This guide is educational, not personalized financial, legal or security advice. A checklist reduces avoidable mistakes; it cannot make a transaction risk-free.
Realized and unrealized gains: keep the definitions separate: the short version
An unrealized gain is generally a valuation increase in an asset still held, relative to a chosen cost basis. A realized gain generally follows a disposal under the accounting method being used. Exact tax and reporting treatment is jurisdiction-specific, so do not treat a generic portfolio label as a legal conclusion.
Scope and limitations
Both calculations depend on reliable acquisition history, prices, fees and classification of transfers. Thinly traded assets may have an attractive displayed price that cannot be realized for the whole position. A chart can therefore show a gain that is difficult to turn into usable funds.
An illustrative case
In an invented example, ten units bought for $5 each are displayed at $8 each. The paper increase is $30 before costs. If selling all ten produces only $74 after execution effects and fees, the actual proceeds differ from the $80 screen valuation.
A no-money review
- Write down quantity, cost basis, reference price and estimated exit costs.
- Separate assets still held from completed disposals.
- Consult a qualified local adviser before using the figures for tax reporting.
Where readers go wrong
Do not assume transferring between your own wallets is automatically a sale, or that every platform applies the same cost-basis convention.
A closer check
Realized and unrealized figures answer different questions. A current balance may be valued at a chosen price, while realized gains depend on which units were sold and how transfers are treated. Write the valuation time, currency, cost-basis method and fee treatment before comparing two wallets or two periods.
For a related next step, see onchain claim checklist.
The practical takeaway
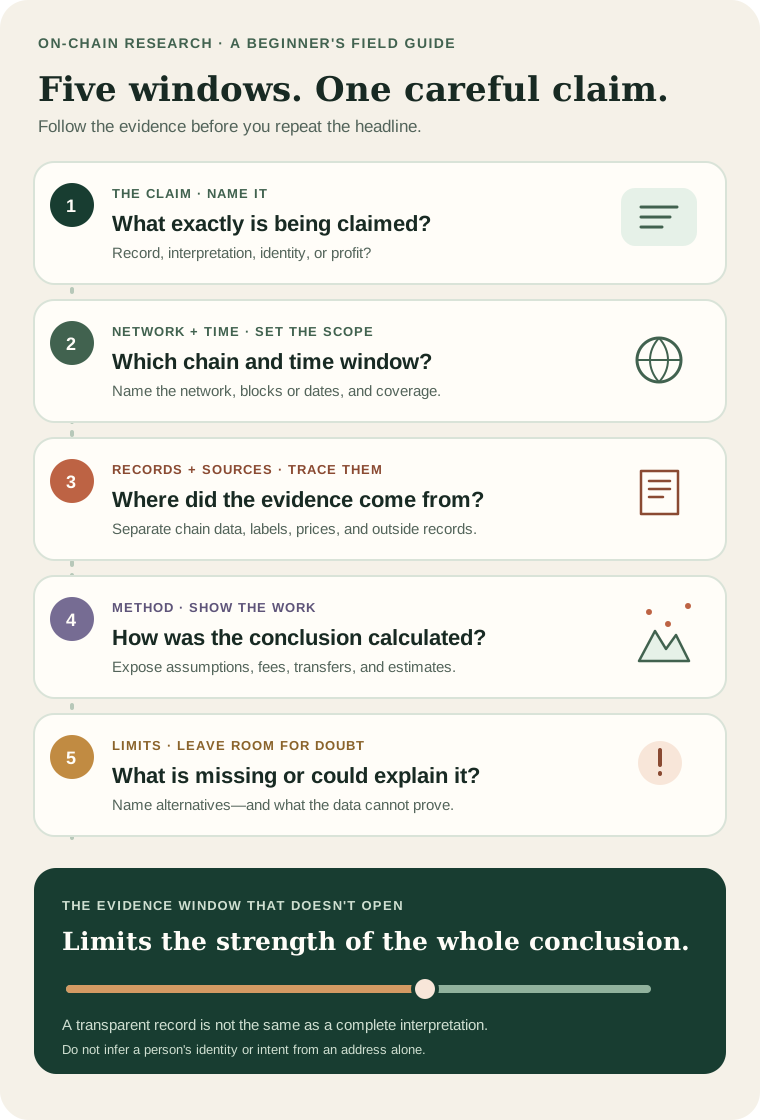
Public records show particular addresses and transactions, not the whole financial life or intent of a person. Labels, valuations and profit calculations add assumptions. Treat an observation as evidence with a boundary. Do not identify an individual, copy a trade or accuse someone of misconduct from one address alone.
Check your understanding.
What can make an unrealized gain differ from eventual proceeds?
A correct answer records local learning progress, not a qualification or proof of financial readiness.
Put this lesson in context
Start with an explorer record, then distinguish the recorded event from assumptions about a person or project.
Sources & context
- Bitcoin.org — Some things you need to know ↗Consulted 2026-10-11
- StonkBuilder — SuperQuant public workflow and FAQ ↗Consulted 2026-09-23
Original educational content prepared for this project. Sources provide context, not endorsement or a guarantee that every statement remains current. Rules, product interfaces and availability can change.
Keep learning in Telegram.
Open this published guide in the learning bot. No account connection or wallet is needed.
Join the $STONKB community.
Follow project updates, share useful ideas and meet other builders. You do not need to buy $STONKB to join.
Take what you learned.
Leave the pressure behind.